
Navigating Risk: Asset Protection and Legal Rights After an Accident
The Intersection of Liability and Wealth Preservation
Life is full of unexpected twists. A single accident or unforeseen event can suddenly expose your hard-earned assets to significant financial risk. With millions of lawsuits filed in the United States each year, protecting what we’ve built is not just a concern for the wealthy; it’s a vital part of responsible financial planning for everyone.
We often think of legal rights only after an incident, but true security comes from understanding how to proactively shield our assets. This guide will explore the essential strategies and legal considerations for asset protection, focusing on how we can safeguard our financial future when facing potential liabilities, especially in the wake of an accident. From understanding the nuances of various legal tools to knowing when and how to act, we’ll equip you with the knowledge to build a robust defense for your wealth. For instance, ensuring we have robust coverage, including something like Stanton auto insurance protection, can be a crucial first step.
The sheer volume of litigation in the United States—over 40 million lawsuits filed annually—underscores a critical reality: our assets are constantly exposed to potential claims. This statistic isn’t meant to cause alarm, but to highlight the necessity of proactive financial security and risk management. Litigation trends show that individuals and businesses alike can face unexpected legal challenges, from personal injury claims to business disputes, professional malpractice, or even divorce.
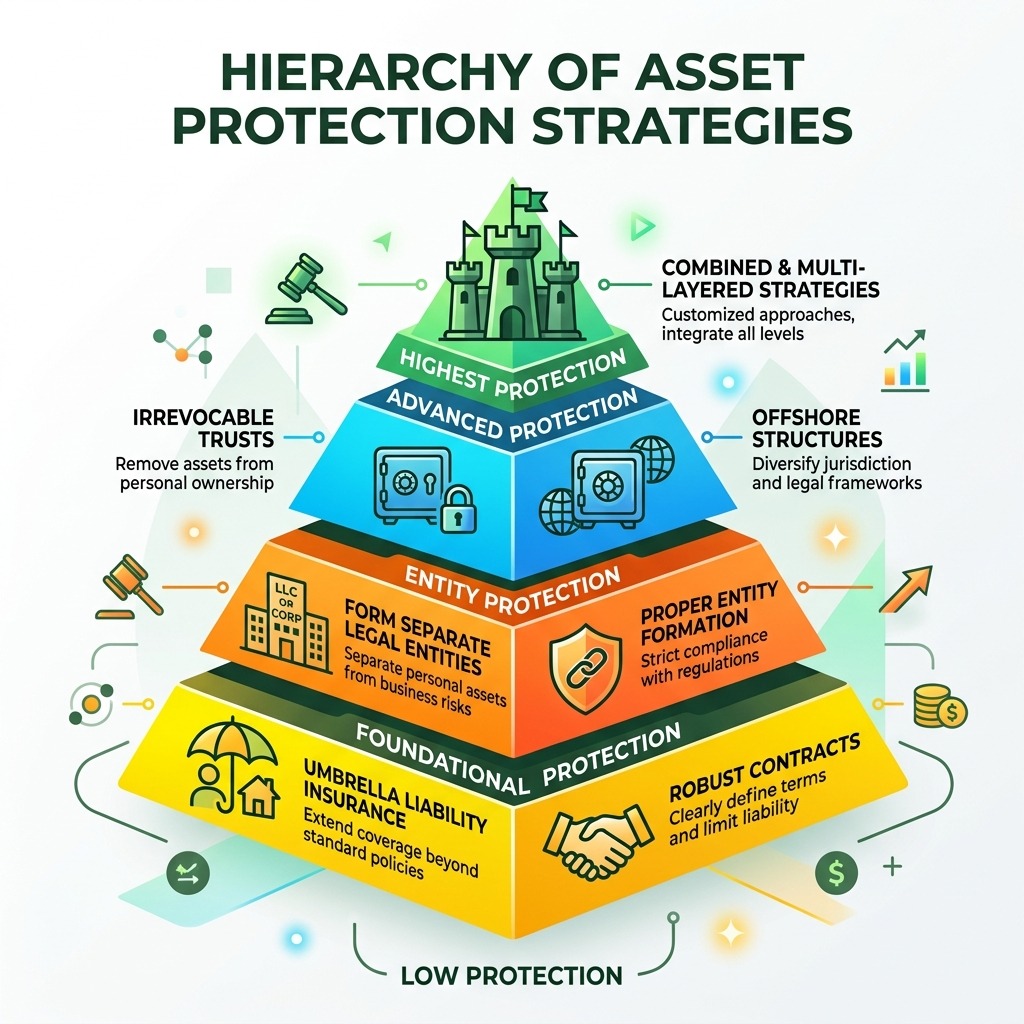
Proactive planning, therefore, isn’t a luxury; it’s a fundamental component of wealth preservation. Just as we insure our homes and vehicles against physical damage, we must also “insure” our financial well-being against legal threats. This involves understanding the various layers of protection available and strategically implementing them before a crisis hits. Think of it as building a robust financial firewall, not just for specific events, but across our entire financial landscape.
Understanding Asset Protection and Legal Rights in the Modern Economy
Asset protection refers to a set of legal strategies and planning techniques designed to legally shield an individual’s or business entity’s wealth from potential creditors, lawsuits, judgments, and other liabilities. It’s about arranging our finances in a way that makes it difficult for future creditors to seize assets, without engaging in illegal activities like tax evasion or perjury.
It’s crucial to distinguish asset protection from estate planning and bankruptcy. While asset protection strategies are often integrated into a comprehensive estate plan, their primary focus differs. Estate planning typically concerns the orderly transfer of assets upon death, minimizing estate taxes, and ensuring our wishes are carried out. Asset protection, on the other hand, is about safeguarding assets during our lifetime from unforeseen liabilities. Similarly, asset protection is a proactive measure taken before a claim arises, whereas bankruptcy is a reactive legal process initiated to discharge existing debts when financial distress has already occurred. The goal of asset protection is to avoid bankruptcy altogether by making our assets less attractive or accessible to creditors. For those who unfortunately find themselves as injury victims, understanding how to protect their recovery and existing wealth becomes paramount, and resources such as those focused on Protecting injury victim assets can provide essential guidance.
A cornerstone of effective asset protection planning is a thorough understanding of fraudulent transfer laws, primarily the Uniform Fraudulent Transfer Act (UFTA) or its successor, the Uniform Voidable Transactions Act (UVTA), adopted in most U.S. states. These laws aim to prevent debtors from transferring assets out of their name with the intent to hinder, delay, or defraud creditors. Courts look for “badges of fraud” – circumstantial evidence that suggests an intent to defraud, such as transfers made to insiders, transfers where the debtor retains control, or transfers made shortly before or after a debt was incurred. This is why timing is critical: asset protection measures must be implemented when we are financially solvent and not facing an imminent claim.
The distinction between legal title and beneficial interest is also central to asset protection. Assets to which we do not hold legal title (e.g., assets held in an irrevocable trust or by a nominee entity) are generally beyond the direct reach of creditors. This legal separation forms the basis for many asset protection strategies.
Statutory Shields: Homestead Exemptions and Retirement Accounts
Many jurisdictions offer statutory protections that automatically shield certain assets from creditors. These “exempt assets” form the first line of defense in an asset protection plan.
Homestead Exemptions
A homestead exemption protects a portion or all of the equity in our primary residence from being seized by creditors. The extent of this protection varies dramatically by state. Some states, like Florida, offer an unlimited homestead exemption, meaning the entire value of a primary residence (up to specific acreage limits) is protected from most judgment creditors. This can be a powerful shield for homeowners. In contrast, other states have more modest limits.
For example, in Massachusetts, the standard homestead exemption is $125,000, but it can be increased to $500,000 by filing a Declaration of Homestead. New Hampshire provides a homestead exemption of $120,000. These amounts, while significant, are not unlimited. Understanding the specific limits and requirements in our state is crucial.
| State | Standard Homestead Exemption (Equity) | Notes [TABLE]
Advanced Strategies: Trusts and Business Entities
Beyond basic exemptions, sophisticated asset protection often involves the strategic use of trusts and business entities. These tools allow for greater control over asset exposure and can provide robust shields against future liabilities.
Domestic Asset Protection Trusts (DAPTs)
Domestic Asset Protection Trusts (DAPTs) are a powerful tool for individuals seeking to protect their assets while retaining some beneficial interest. Unlike traditional irrevocable trusts, DAPTs allow the grantor (the person who creates and funds the trust) to be a discretionary beneficiary. This means we can potentially receive distributions from the trust, but the assets are generally protected from our creditors.
However, DAPTs are not universally recognized across the U.S. Currently, 14 U.S. states allow the creation of DAPTs: Alaska, Delaware, Hawaii, Missouri, Nevada, New Hampshire, Ohio, Oklahoma, Rhode Island, South Dakota, Tennessee, Utah, Virginia, and Wyoming. Each state has its own specific statutes governing DAPTs, with varying “seasoning periods” (the time that must pass after assets are transferred into the trust before they are fully protected) and exceptions for certain types of creditors (e.g., child support, alimony, tort claims). New Hampshire, for example, has well-established DAPT statutes that offer strong protection. Choosing the right jurisdiction for a DAPT is a critical decision that requires careful legal analysis.
Limited Liability Companies (LLCs) and Charging Orders
Limited Liability Companies (LLCs) are a popular choice for asset protection, particularly for business owners and real estate investors. An LLC separates the business’s liabilities from our personal assets. If the business is sued, our personal home, savings, and other assets are generally protected.
For multi-member LLCs, the primary protection against a member’s personal creditors is the “charging order.” This legal remedy allows a creditor to only claim the distributions from the LLC that would normally go to the debtor-member. The creditor cannot force the sale of the LLC’s assets or take control of the LLC’s operations. This effectively makes the LLC interest unattractive to creditors. However, maintain strict corporate formalities to prevent creditors from “piercing the corporate veil,” which would allow them to reach the personal assets of the owners.
Irrevocable Trusts and Spendthrift Provisions
Irrevocable trusts are a cornerstone of advanced asset protection. Once assets are transferred into an irrevocable trust, they are generally removed from our personal estate and are no longer considered our property for creditor purposes. This means they are typically beyond the reach of lawsuits and judgments.
A key feature of many asset protection trusts is a “spendthrift provision.” This clause legally prevents beneficiaries from assigning or transferring their interest in the trust to creditors. It also prevents creditors from attaching or garnishing the trust assets. While we lose direct control over assets placed in an irrevocable trust, a well-drafted trust can still provide for our needs and those of our beneficiaries, often through an independent trustee with discretionary powers.
Offshore Trusts
For individuals with substantial assets and a high-risk profile, offshore trusts (also known as international asset protection trusts) can offer an even higher level of protection. Jurisdictions like the Cook Islands are renowned for their robust asset protection laws, which can make it exceptionally difficult for foreign creditors to enforce judgments against trust assets. These trusts typically involve transferring assets to a trustee in a foreign jurisdiction, governed by that jurisdiction’s laws. While powerful, offshore trusts are complex, expensive to establish and maintain, and come with significant tax and reporting obligations to the IRS. They are generally considered for those with liquid assets exceeding $1 million.
Proactive Defense: Insurance and Timing
While legal structures like trusts and LLCs form the foundation of asset protection, insurance acts as a crucial first line of defense, often preventing claims from escalating to the point where our personal assets are threatened.
read more : https://lawhubx.com/
Integrating Insurance with Asset Protection and Legal Rights
Umbrella liability policies are perhaps the most overlooked yet vital component of a comprehensive asset protection strategy. These policies provide excess liability coverage above the limits of our standard home, auto, and other primary insurance policies. If a major lawsuit exhausts the limits of our underlying policies, the umbrella policy kicks in, providing an additional layer of protection, often ranging from $1 million to $5 million or more. This can be invaluable in covering legal defense costs, settlements, and judgments. For instance, in an auto accident, while our primary Stanton auto insurance protection covers initial damages, a severe incident could easily exceed those limits, making an umbrella policy indispensable.
Beyond umbrella policies, professional malpractice insurance is essential for individuals in high-risk professions (e.g., doctors, lawyers, accountants), protecting them from claims arising from their professional services. Comprehensive general liability (CGL) insurance is critical for businesses, covering bodily injury, property damage, and advertising injury claims.
The integration of insurance with other asset protection tools is key. For example, if an irrevocable trust holds certain assets, insurance policies can be structured to protect those assets within the trust, or the trust itself can be the beneficiary of certain policies. This layering of protection ensures that multiple defenses are in place.
Navigating State-Specific Asset Protection and Legal Rights
The effectiveness of any asset protection plan is heavily influenced by state laws. As we’ve seen with DAPTs, only certain states permit them. Even for common tools like LLCs, state laws vary regarding charging order protections. For instance, some states offer stronger charging order exclusivity than others, making them more attractive for asset protection. States like Alaska, Delaware, Nevada, and South Dakota are often cited for their favorable asset protection laws, not just for DAPTs but also for other entity protections.
Local court precedents also play a significant role in how asset protection strategies are interpreted and enforced. What might be effective in one state could be challenged differently in another. Therefore, seeking counsel from an attorney well-versed in the specific laws of our state, and potentially other relevant jurisdictions, is paramount.
When implementing an asset protection plan with an attorney, several steps are crucial:
- Comprehensive Asset Inventory and Risk Assessment: We must identify all assets (personal, business, liquid, illiquid) and evaluate potential liabilities from our profession, lifestyle, and business activities.
- Documenting Solvency: It’s essential to establish and document our financial health before implementing transfers. This provides evidence that transfers were not made with fraudulent intent.
- Choosing the Right Tools: Based on our risk profile and asset types, an attorney can recommend appropriate strategies, whether it’s an LLC, a specific type of trust, or maximizing statutory exemptions.
- Maintaining Corporate Formalities: For business entities like LLCs, strict adherence to operating agreements, record-keeping, and separation of personal and business finances is vital to prevent “piercing the corporate veil.”
- Regular Review and Maintenance: Asset protection plans are not set-it-and-forget-it. Life changes, laws evolve, and our financial situation shifts. Regular reviews with our attorney are necessary to ensure the plan remains effective and compliant.
Frequently Asked Questions about Asset Protection and Legal Rights
How does asset protection differ from bankruptcy?
Asset protection is a proactive strategy to shield wealth from future creditors while maintaining control, whereas bankruptcy is a reactive legal process to discharge existing debt through court-supervised liquidation or reorganization. Asset protection aims to prevent the need for bankruptcy by making assets less accessible to potential claimants.
Are retirement accounts like IRAs and 401(k)s protected from lawsuits?
Under federal ERISA law, 401(k) plans and other qualified employer-sponsored retirement plans enjoy near-absolute protection from creditors, with limited exceptions (e.g., QDROs, IRS levies). IRAs are protected up to $1,512,350 (subject to inflation adjustments) in bankruptcy proceedings under federal law. However, for non-bankruptcy judgments, state laws dictate the level of protection for IRAs, which can vary significantly.
When is it too late to implement an asset protection plan?
A plan must be implemented before a “claim” arises or before there is a reasonable expectation of a claim. Transfers made after an accident, after being served with a lawsuit, or when facing imminent financial distress are often deemed fraudulent conveyances and can be reversed by a court, potentially exposing us to further penalties. Proactive planning while financially solvent is key to legal and effective asset protection.
Conclusion
In an increasingly litigious world, understanding and implementing robust asset protection strategies is no longer optional; it’s a necessity for long-term financial security and peace of mind. From leveraging statutory shields like homestead exemptions and retirement account protections to employing advanced tools like domestic asset protection trusts and limited liability companies, a layered approach offers the strongest defense. Integrating comprehensive insurance coverage, such as umbrella policies, further fortifies our financial fortress.
The journey to effective wealth preservation requires legal compliance, strategic layering, and, most importantly, professional guidance. By working with experienced legal and financial advisors, we can navigate the complexities of state laws, fraudulent transfer rules, and the nuances of various protective structures. Proactive planning, executed judiciously and ethically, ensures that our hard-earned assets remain secure, safeguarding our legacy for ourselves and our loved ones against life’s unpredictable challenges.